Canadian Prime Minister Mark Carney has announced a major expansion of business tax incentives that addresses an issue TRSA members have been advocating for. This expansion could significantly benefit TRSA members investing in equipment, technology and facility modernization.
Speaking at the Canadian Investment Summit, Prime Minister Carney unveiled the Productivity Mega Deduction, which would allow businesses to immediately deduct the full cost of most eligible capital investment on or after Sept. 15. The proposal significantly expands immediate-expensing provisions introduced in Budget 2025 and is intended to encourage business investment and improve Canada’s competitiveness.
For Canada’s industrial laundry sector, the change should have a meaningful impact on future capital investment, as facilities continuously upgrade costly and specialized equipment. Under previous manufacturing-focused incentives, however, the industry’s eligibility was uncertain because industrial laundry operations were not clearly recognized as manufacturing or processing for tax purposes.
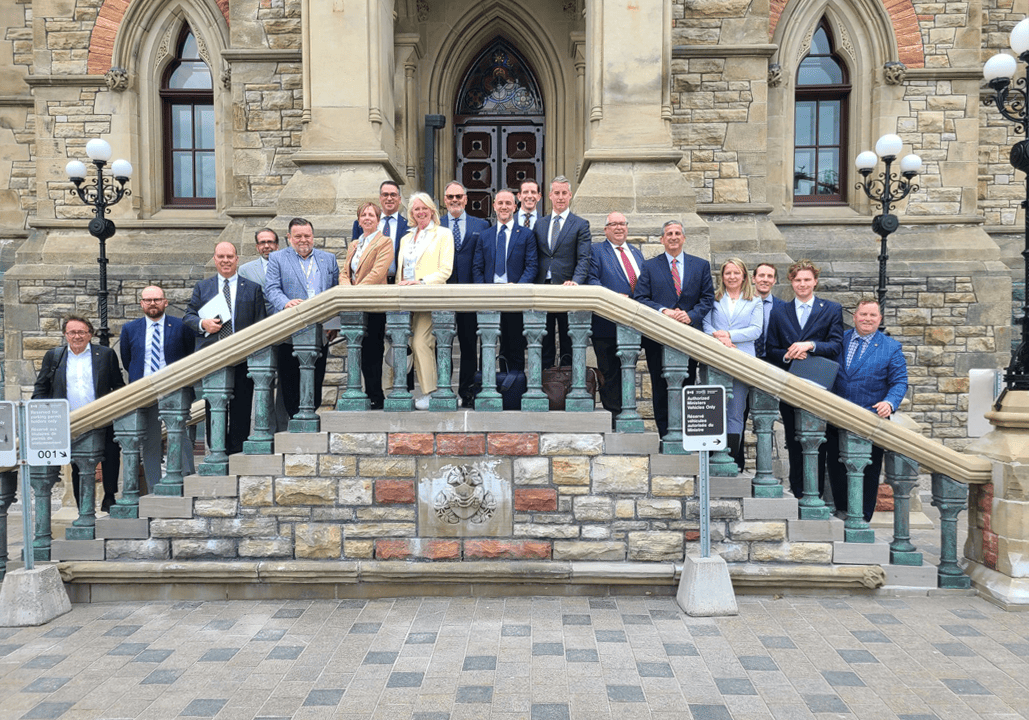
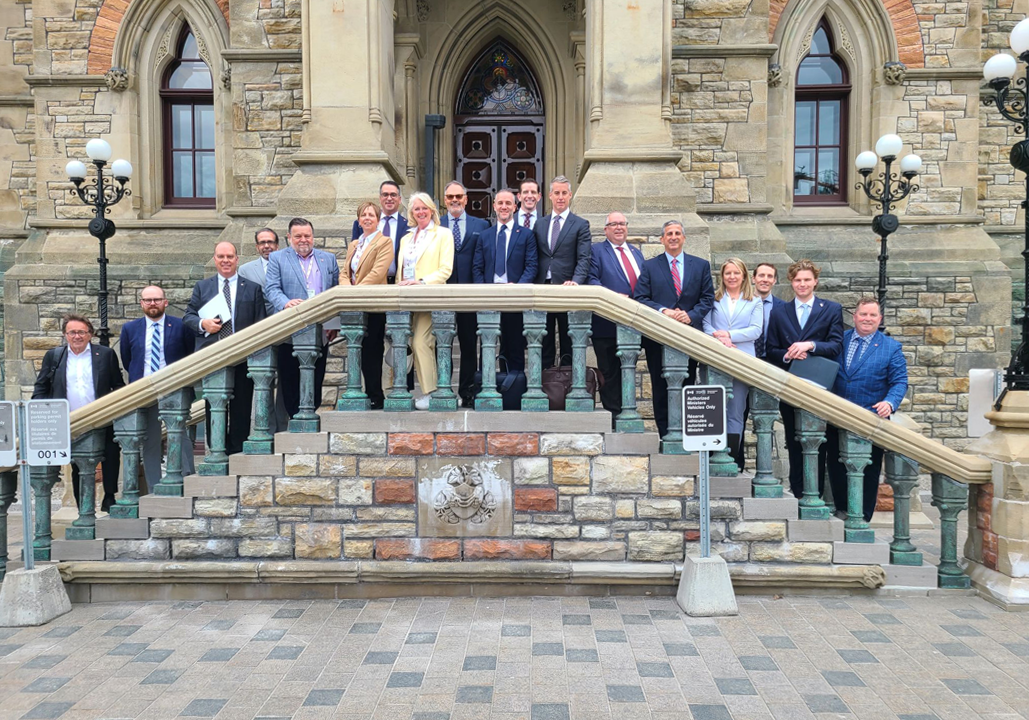
When TRSA initiated the Canadian advocacy program, members identified this issue as a priority. Canadian members have since worked proactively to secure access to this accelerated depreciation. Advocacy efforts have included 12 meetings with Members of Parliament (MP) during TRSA’s Canadian Legislative Summit, three facility tours with local MPs, multiple meetings with Department of Finance officials and submissions through the federal pre-budget consultation process.
During those engagements, TRSA members emphasized the capital-intensive nature of industrial textile processing and the sophisticated systems used to transform soiled or unusable textiles into hygienically clean, market-ready reusable products. Members also highlighted the industry’s role in supporting essential sectors across Canada and the importance of policies that encourage continued investment and growth.
The Productivity Mega Deduction extends immediate expensing to most classes of capital cost allowance-eligible assets regardless of industry classification. As a result, qualifying equipment investments by TRSA members would no longer depend on the industry being classified as manufacturing or processing to receive immediate-expensing treatment.
TRSA will remain engaged as the government moves forward to implement the legislation and will continue advocating for policies that support investments and competitiveness in Canada’s linen, uniform and facility services industry. The announcement represents meaningful progress for Canadian operators and follows sustained engagement by TRSA members to ensure policymakers understand the industry’s capital needs, economic impact and importance to Canadians’ daily life.
Questions? Contact TRSA’s Vice President of Government Relations Kevin Schwalb [email protected] or Advocacy Manager Sean Kearney at [email protected].
Sign Up For Our Newsletter
Receive the latest updates on the linen, uniform and facility services industry from TRSA delivered straight to your inbox.