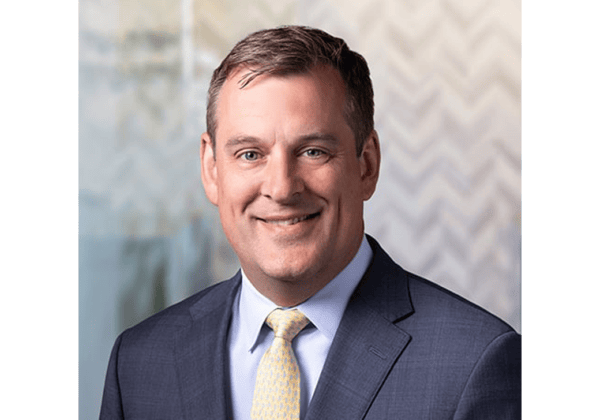
 Andrew Wittmann, senior research analyst, Robert W. Baird & Co., gives an update on economic trends in the linen, uniform and facility services industry, including an overview of the potential Cintas and UniFirst deal and its impact on the marketplace. Baird partners with TRSA to publish a quarterly report on economic trends in the industry. For more information and to participate in the survey, contact Wittmann at [email protected].
Jason Risley: Welcome to the Linen, Uniform & Facility Services Podcast – Interviews & Insights by TRSA. Today’s episode features excerpts from a recent presentation given by Robert W. Baird & Co. Senior Analyst Andrew Wittmann at TRSA’s 2026 Annual Conference & CEO Summit in Napa, California. In addition to discussing industry economic trends, Wittmann breaks down one of the biggest stories of the year in the industry: Cintas’ long pursuit of UniFirst – a deal now under federal review with major implications for competition and growth across the marketplace. Wittmann unpacks the numbers behind the deal, what it could mean for industry players and why investors still see uncertainty. Plus, he dives into Vestis’ surprising rebound and whether it signals a real turnaround. Let’s get into it.
Andrew Wittmann: Everybody wants to talk about, twisting my ear these last couple of days, talking about Cintas and UniFirst. Everybody wants to know what’s happening, so do I. The latest, most recent thing started a year and a half ago when Cintas sent a nonbonding offer to UniFirst for $275 a share. UniFirst didn’t talk to them. Cintas comes back in January last year, says, hey, we’ll do really whatever you want. You want board seats, you want to keep your brand. They said lots of things. UniFirst doesn’t engage, says go away. Cintas then basically laid out all the letters that they sent to UniFirst in a public filing and said, here’s all the letters; we’re trying to get them to sell. Basically, trying to convince their shareholders that they’re trying to do the right thing, which is to try to buy UniFirst. They’re just showing, they’re like, hey, we’re trying here. These guys won’t talk to us. So, they just threw all the memos out there and said, look at, here’s how it’s going. And then they gave up in March and last summer. UniFirst results weren’t very good again. And investors at UniFirst, like there’s all these people that were not part of the super voting family shares that were along for the ride and they’re pulling their hair out. They’re like, we can get a lot of money for these shares and the family didn’t want to sell. And you all know the saga, so I’m not going to get into much, but investors are frustrated. So, then an activist investor came in at UniFirst. And now the activist investor has the problem that his last name is the wrong last name, but he was able to convince enough other shareholders to just basically publicly run a huge campaign and say, this needs to happen, and you’re breaching fiduciary duty and threaten to sue. There’s really no grounds to sue, but you threaten to sue if you’re trying to get people to do what you want. It was kind of a mess. It’s not a secret that Mike Croatti flipped against other family members. Not stuff that you want to go through, certainly in public. After all that, Cintas makes another offer in December 2025 for $275 a share. And it wasn’t until March where, frankly, I was surprised. There was a board campaign. They were trying to get board seats. It didn’t happen. But the family decided to change their mind in March of 2026, just a couple of months ago. Right now, it’s under antitrust for review by the Federal Trade Commission. I know that several people in this room have probably gotten phone calls from the Federal Trade Commission about the competitive nature or anti-competitive nature of this transaction. which is still pending. We won’t really know until June 11 whether or not the FTC is going to throw the full weight of the organization and the federal government behind prosecuting this. It’s still in the early investigation process. So that is the latest and greatest in terms of what’s happening on this one. But I would just say that UniFirst shareholders are slated to get $155 in cash plus 0.772 shares of Cintas. That equated at the time of the announcement to about $310 per share. And what’s significant about that is that was almost a doubling of the share price at the time. If you go back to the unaffected share price, they basically doubled the share price. 87% is the technical number. 2.4 times UniFirst revenue. This was about 18 times their trailing EBITDA. But if you throw in the synergies, which is the way you look at it from Cintas’ point of view, Cintas is going to be paying about eight times EBITDA on $375 million of synergies. Lots of numbers, but listen to this. Think about this for a second. UniFirst EBITDA was $330 million. Cintas said they’re going to have $375 million of synergies. That number is probably about 10% too light. Let’s call it $400 million of synergies. And Cintas also said, we don’t know what the revenue synergies are. We might know what they are, but we’re not going to tell you. That’s for us to keep, not for you to get. And I think that that’s probably another $300 million right there. So, if you think about this, it is massively accretive to the profits at Cintas. I just told you that they’re going to take $300 million of EBITDA and add 300 and another 300 or probably more. It’s a lot of profits that will ultimately come from this deal. If it closes according to plan, it’ll close later this year. We’ll see what happens. The stock market is saying if you look at the stock prices, because it’s a stock for stock deal, the stock market is saying there’s about a 70% chance that the deal goes through and about a 30% chance that the deal does not go through. You can do the math and kind of do that kind of math. Which also is super interesting, despite paying a really big number for UniFirst, Cintas’ balance sheet at the end of this deal, when the deal closes, is still going to have the ability to invest substantially in all kinds of things, including even buying their own stock. Their EBITDA is going to be about 1.5 times the amount of debt that they have, which is super low. Cintas will not be biting an eye financially to take this thing down. Part of that is aided by the fact that they’re delivering stock instead of paying all cash for sure. But I would just mention that this is not financially a stretch whatsoever for Cintas to pull this off. But if you had curiosity as how all the math works out in terms of how this accretes to shareholders at Cintas, we’ve run the numbers. And what it does is it basically increases at least 20% when it’s all said and done. A couple other things, just for a long time, Cintas was solidly green, beating and raising expectations. That’s why the stock has been good for a really long time. Recently they haven’t been doing that. This has been a tough stock at Cintas. It’s down an awful lot since the announcement of the deal. It’s because their profits have not been surprising investors by nearly enough to maintain a very lofty valuation or PE ratio. Over at UniFirst, you heard me say last year, the last couple years, that these guys over at UniFirst were missing numbers a lot. In recent times, they’re doing a little bit better in terms of hitting analyst expectations. So, the stock is obviously only depending on the takeout price of the deal, but they were starting to deliver more consistently. Here’s my general comment on the competitive impact of Cintas. So, Cintas has already reached what I’d call terminal velocity, right? If they wanted to use their market weight and their ability to have 28% EBITDA margins against everybody else’s 10 or 15, they could have totally done that already. So, one of the best things about the industry structure, in my opinion, and I’d be curious if you all agree, is when I look at Cintas not using their leverage and their pricing power, that they could just destroy everybody. By being generally a premium pricer that’s aggressive on the revenue line, that’s allowed everybody to still have a role here. That was achieved when they did G&K and probably honestly a little bit before G&K. So yeah, UniFirst extends that, but until the ethos of the company gets away from the top-line growth and pushing, pushing, pushing that top line, which is who they are, I just don’t know that really changes it. There are other ramifications, like the vertical integration of Cintas and the supply chain that stands behind UniFirst, particularly on the garment side, I think is something that maybe we all need to think a little bit about. I think Cintas is going to continue to be that premium revenue pusher in the marketplace. As it relates to divestitures, in the research notes that I’ve written, I’ve alluded to the fact that I do think that a likely outcome, or maybe I think I said the most likely outcome is going to require some level of divestiture. Divestitures are great from a legal point of view because everybody gets to claim victory in this scenario, right? Government says, hey, we really went after them and didn’t get this. And Cintas says, yeah, we had to settle, but we still got what we wanted. Who knows how it goes. But it stands to me, and there’s some precedent cases out there in business services at the branch level. There’s a company, Iron Mountain, the document storage company, that did a large acquisition about 10 years ago, and they paid 100% for the company, and they got about 95% of the EBITDA after the divestitures. Super good precedent case, in my opinion. If Cintas gets 95% of UniFirst, I think everybody claims victory. In terms of the ramifications and the opportunities, I have no idea where the prices are going to go. Three times revenue seems like a lot when it’s a forced sale. I would imagine that anything that comes out of a forced sale would be done at a good valuation. Obviously, any company that’s going to look at them is going to have to have the strategy, say, can we make this market work? Are we just going to buy something? We’re going to lose the customers later to a dominant Cintas, and all those things. I’m thinking you usually get a pretty good deal. For maybe an independent in the market or a regional, these could be some pretty great opportunities, especially if they come with a plant, because they might come with a plant, and these are pretty good plants by and large. And then Vestis, we’re going to talk a lot about Vestis. Everybody wants to know, stock was up 30% yesterday. Everybody was like, why was it up? I’ll talk about that in a second. Vestis, after they spun off as a public company, it was probably the most breathtaking I’ve seen in 20 years of how fast we were lowering estimates at Vestis. We were cutting our estimates by dramatic amounts very, very rapidly. When you do that for a couple of years and expectations on stocks get super-duper low, it doesn’t take much to light them on fire to when they get a little bit better. That’s what happened yesterday. So, we’ll talk about that here in a second. These are the current trading multiples of the publicly traded companies. Cintas trading at 22 times EBITDA. Vestis down today around eight times EBITDA. Even after the move, still about eight times EBITDA on a go-forward basis. This is just kind of a comparison of the relative sizes of the big three, $8 billion for Cintas and Vestis 2.7, 2.2, 2.3 for UniFirst. The thing that always sticks out the most here, in my opinion, is not the revenue sizes because we kind of all know that. The thing that always sticks out the most to me is the profit margins, adjusted EBITDA margins in the upper 20s for Cintas versus around 10 for the other two. If you look at how the profit margins have changed over time, Cintas have really, and this is 15 years of data, Cintas has gone up a lot. The others have gone down, which is an interesting conclusion, maybe not totally surprising. But it really shows how the industry has diverged on the big national players. You can see the organic growth rates for the companies are comparable. Yesterday, Vestis was actually -2 instead of -3. So, like less bad is sometimes good enough to get stocks. And honestly, it was. It was part of the reason the stock went up yesterday. The margins, the key, the reason the stocks went up yesterday is their margins went up yesterday at Vestis and actually went up by a pretty decent amount. That was the reason that the stock went up a lot. It’s crazy to see a uniform rental company go up 30% in one day. I’ve never seen that happen. There was short interest, so people were shorting the stock. There’s a lot of financial leverage on the company. When you do that, the math just works out that the equity has to go up a lot when you get a big revision in estimate. So anyway, I’ll talk about some of these things like the stock yesterday up 30%. So, we were thinking in 2027 that the EBITDA was going to be around $320 million. Turns out that after they stopped the bleeding with their margins yesterday, we got some confidence that like the bottom might be in and we raised our 2027 estimate to like $360 million. That’s a really big change for a one-day change in a uniform rental company’s EBITDA for a year. So, like I told you, the move yesterday was totally justified. It could have gone up even more. So, it wasn’t the wrong move is what I would say. Okay, so just as it relates to Vestis, in case you haven’t been paying attention, they actually do have a new CEO. This is their second CEO that they’ve had since they spun off. And he was the former COO from UPS. He was retired in Atlanta. They’re based in Atlanta. When they spun off, they moved to Atlanta for the headquarters. I think the guy just wanted a hobby. He kind of made his money. Like he had, he’s a smart guy, kind of knew route density, obviously, at UPS. And he’s like, yeah, let’s see what I can do here. It’s been, it was pretty good. What he’s done here, I know it doesn’t feel good and everybody can say bad things about the company, but when you look at the financials, they’ve really, really stabilized. He’s focused on revenue per pound and cost per pound. He’s honestly, for those of you in the linen business, he’s really starting to de-emphasize that hospitality linen. In cases where he feels like he’s not making enough money, he’s given a number that he wants to do it at and he’s happy to lose it. So, what I’ve heard anecdotally in the last 24 hours is that some people are picking up some of these businesses and seeing that opportunity. He’s trying to mix back to uniforms and get a little bit higher value through their system. The data that we’re seeing from them is working. I would just point out though that this is 99% customer retention. That’s 95% customer retention. And you can see like right when they spun off and it just fell off a cliff and we have some numbers here in the 80% range. This was the problem. This is what deleveraged the whole network. They lost a ton of volume when they basically tried to increase prices too much for too long after COVID. During COVID and inflation, everybody kind of got their thing, but they just kept hitting the button a little bit longer. After a while, customers started looking for alternatives and that’s why they lost so much revenue. So, the organic growth rate started going negative here the last couple of years. At one point, I think it was down 6 or 7 or 8%. Totally by their own lack of service and trying to, when you don’t have quality service and you’re raising the price, people are like, it’s like Twilight Zone. The customer’s like, what are you doing here? And that’s what they had to get through. That’s what led to management turnover and ultimately a huge restructuring plan. You all heard it and saw it in the industry. They laid off a ton of their sales force. They announced a plan to save $75 million mostly in the plant, but also in the back offices to try to get the cost structure right for this new level of business. There was a lot going on. The punchline is there’s a lot going on, but as of yesterday, there’s some signs that they might be getting their arms around the worst of it. That’s really the punchline that I think you should walk away with. It’s getting a little less bad and they’re still working on some other things. They’re actually adding to their sales force. That was one of the announcements that we heard yesterday that they’ve got enough confidence to put what they’re calling market development reps to go for deeper existing customer penetration. This is one of the strategies that they’re going for to invest in the business to find a little bit of growth. You know, a lot of people hoped that the company would get taken out. It didn’t happen, obviously, Cintas went for UniFirst and not Vestis and they’re going to have to go out, and go at it alone. We’ll see how that all plays out.
Jason Risley: That’s it for today’s episode. Wittmann covered the high-stakes Cintas–UniFirst deal, what’s driving the numbers behind it, and how it could reshape the competitive landscape, along with the early signs of a comeback story at Vestis. As always, we’ll be watching how this plays out, especially as regulators weigh in and the industry adjusts to what could be a very different future. Additionally, Baird and TRSA release a quarterly survey that looks at economic trends in the linen rental, uniform rental and healthcare sectors. If you would like to participate in the survey moving forward, contact Baird Senior Analyst Andrew Wittmann at [email protected]. Thanks for listening to the podcast. If you found this episode useful, be sure to subscribe on Apple iTunes and share it with a colleague. We’ll see you next time.
Publish Date
June 4, 2026
Runtime
18 min
Categories
Sign Up For Our Newsletter
Receive the latest updates on the linen, uniform and facility services industry from TRSA delivered straight to your inbox.
Recent Podcasts